What I Wish I’d Known About Scaling Before Building with AI
Slow backtests, blown memory, and the coding habits I wish I’d caught sooner.
READ MORE →Research and practical education for traders, quantitative researchers, and Python developers. Learn to build and test trading systems, evaluate strategies, and verify AI-built software.
Quantitative alpha factor research. Systematic signal discovery, backtesting, and portfolio construction.
EXPLORE →Follow one BTC/USD strategy from market data and research through validation, Alpaca paper execution, scheduling, and monitoring.
EXPLORE FORGE LEARN →Premium trading infrastructure automation. AWS cloud deployment, monitoring, and operations.
DEPLOY →"Working with Brian on a fintech application was a pleasure. Not only is Brian very knowledgeable as a Chartered Financial Analyst, but he was a fantastic resource when it came down to programming the application itself. His Python skills are top notch, and he was able to introduce me to developer tools and practices that I still use today."
"I had the pleasure of working with Brian on our internal fintech application overhaul, where he demonstrated exceptional skills in data analytics and workflow automation. My project requirements were complex and a little fluid. However, his clear communication and proactive approach made collaboration seamless, resulting in a dramatic increase in my trading system's performance."
Slow backtests, blown memory, and the coding habits I wish I’d caught sooner.
READ MORE →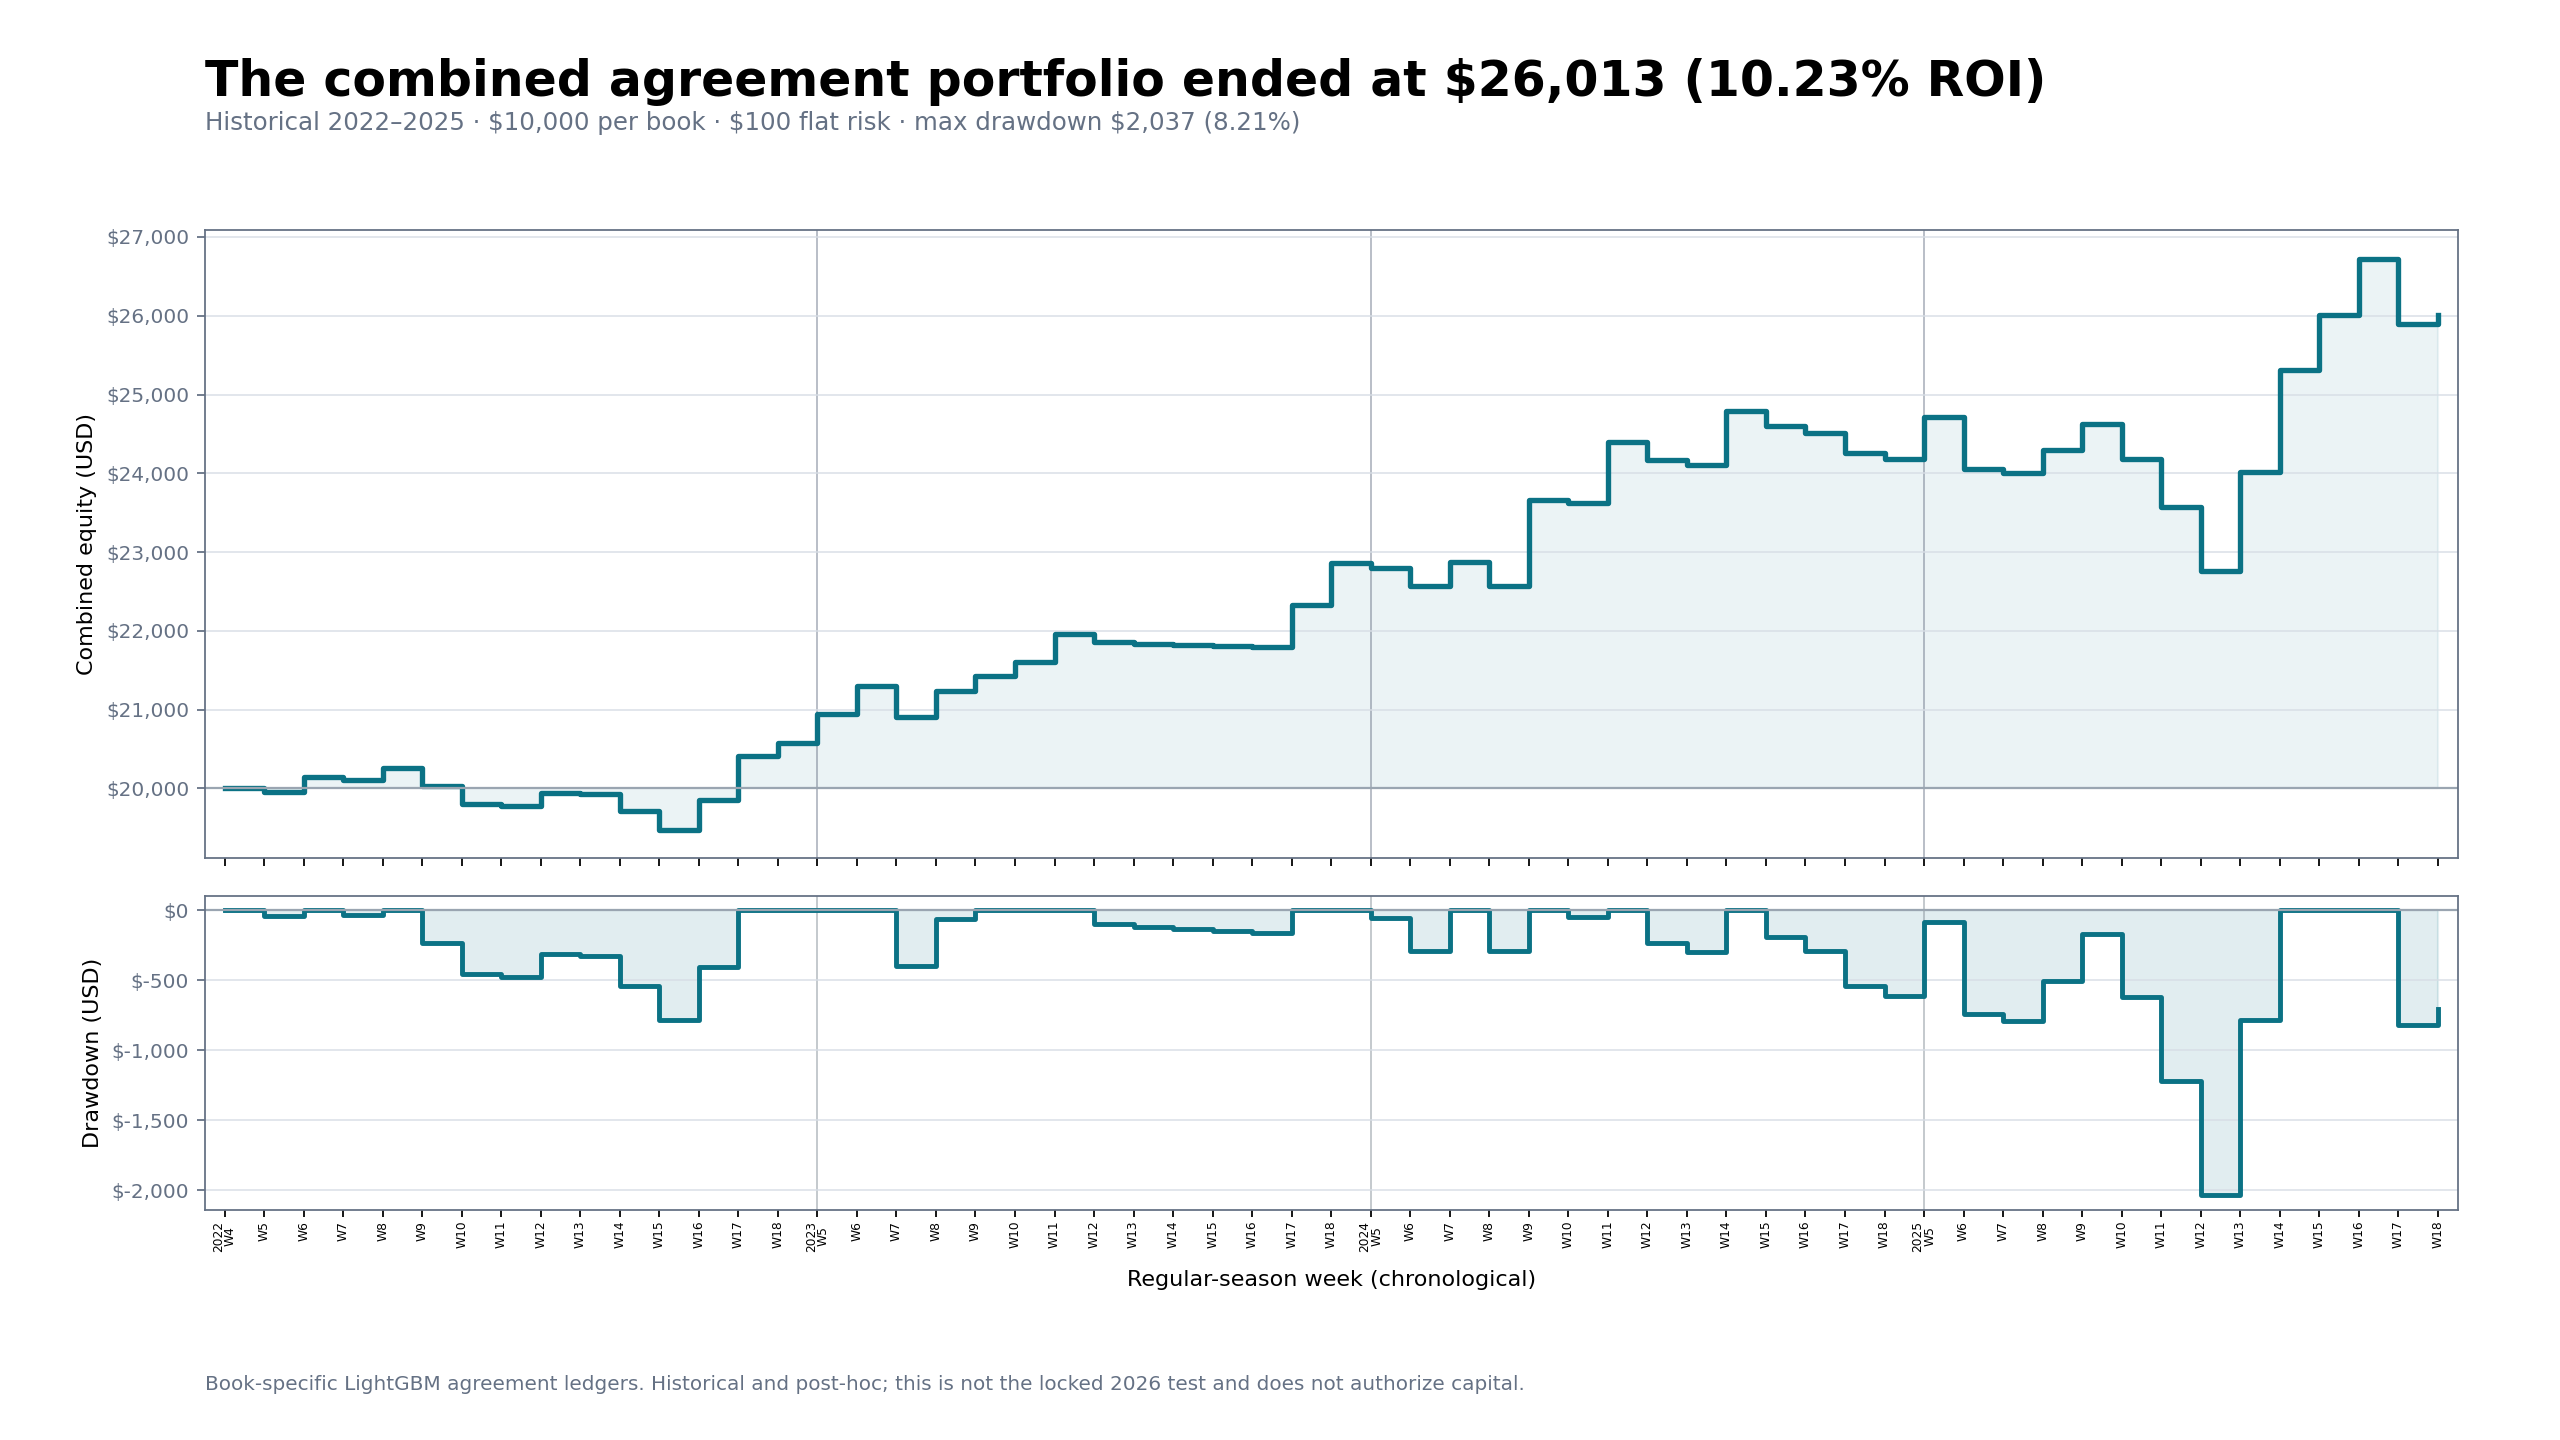
A LightGBM model made money on NFL totals at both FanDuel and DraftKings. The same-side agreement filter looked stronger, but its historical edge is a lead for one locked 2026 test, not a betting strategy.
READ MORE →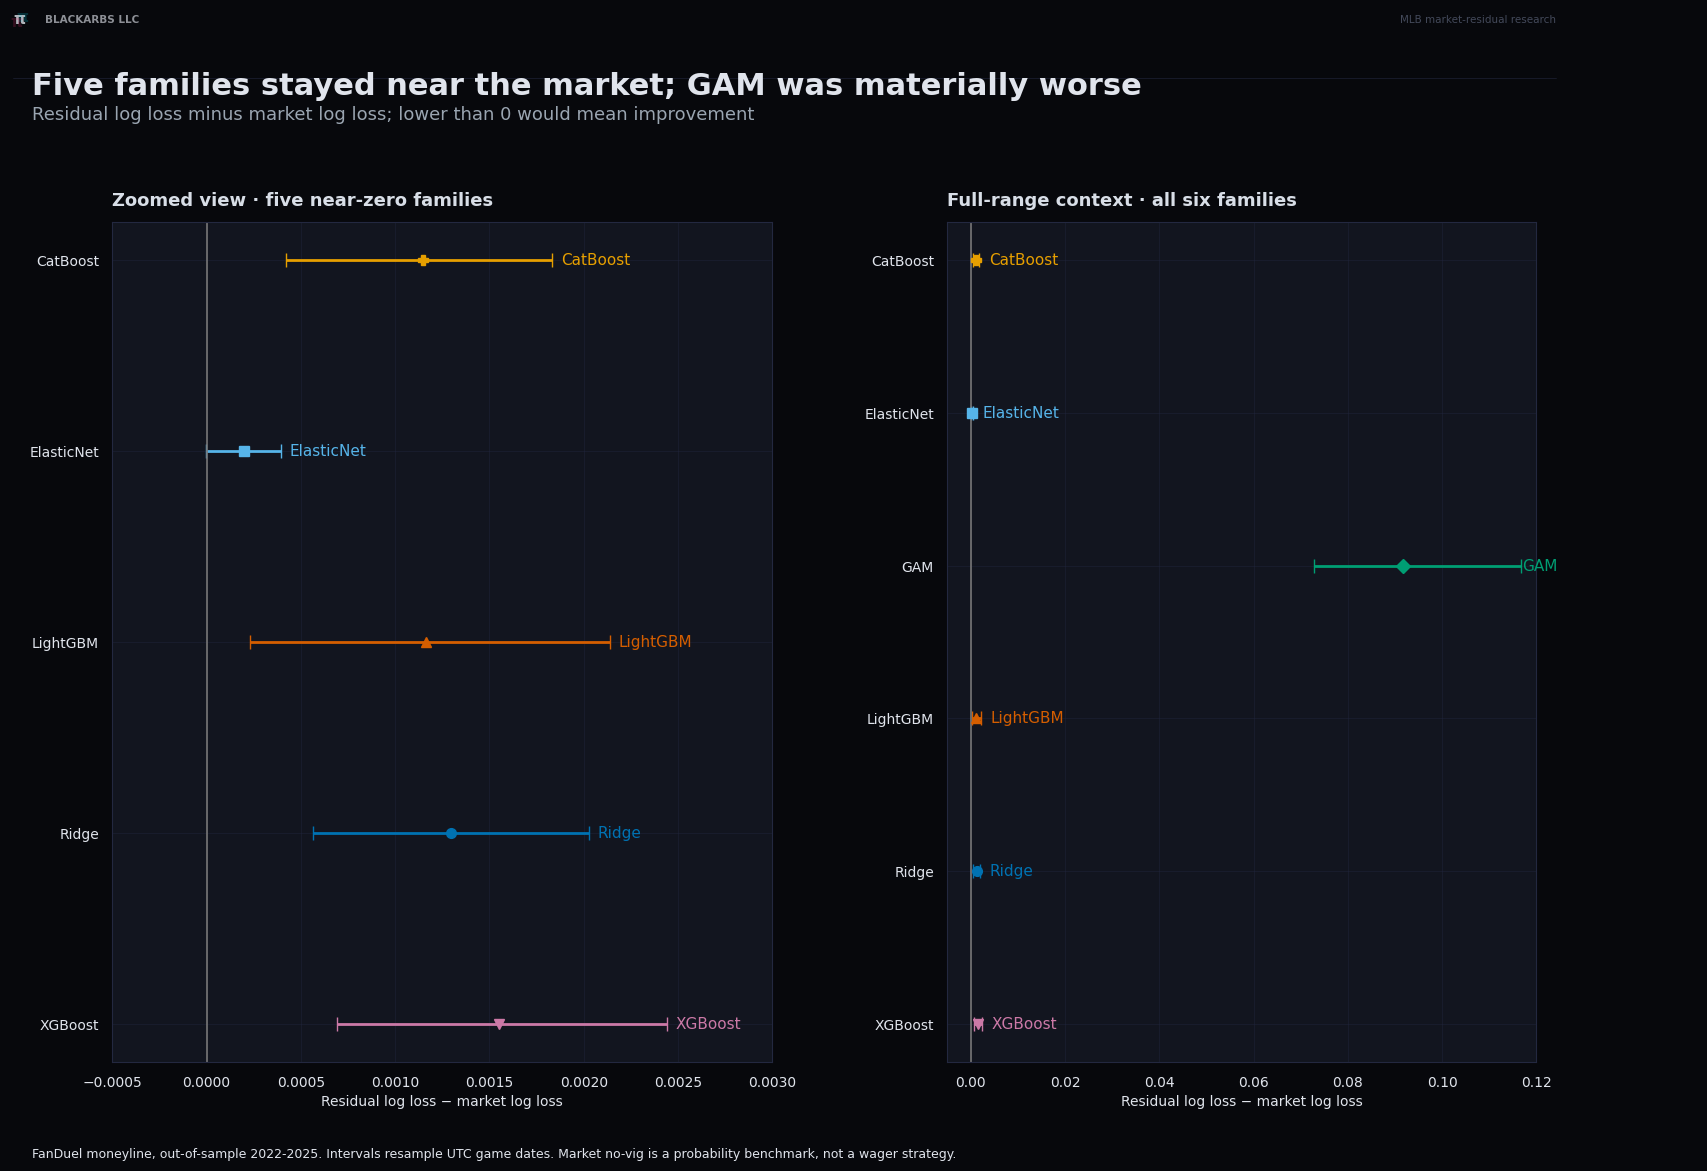
Two MLB models were profitable in a corrected 2022–2025 backtest. That is a lead worth following, not proof of an edge. Their plausible profit ranges still included losses, so the right next move is one locked-down test on new games, not another model sweep, and not capital.
READ MORE →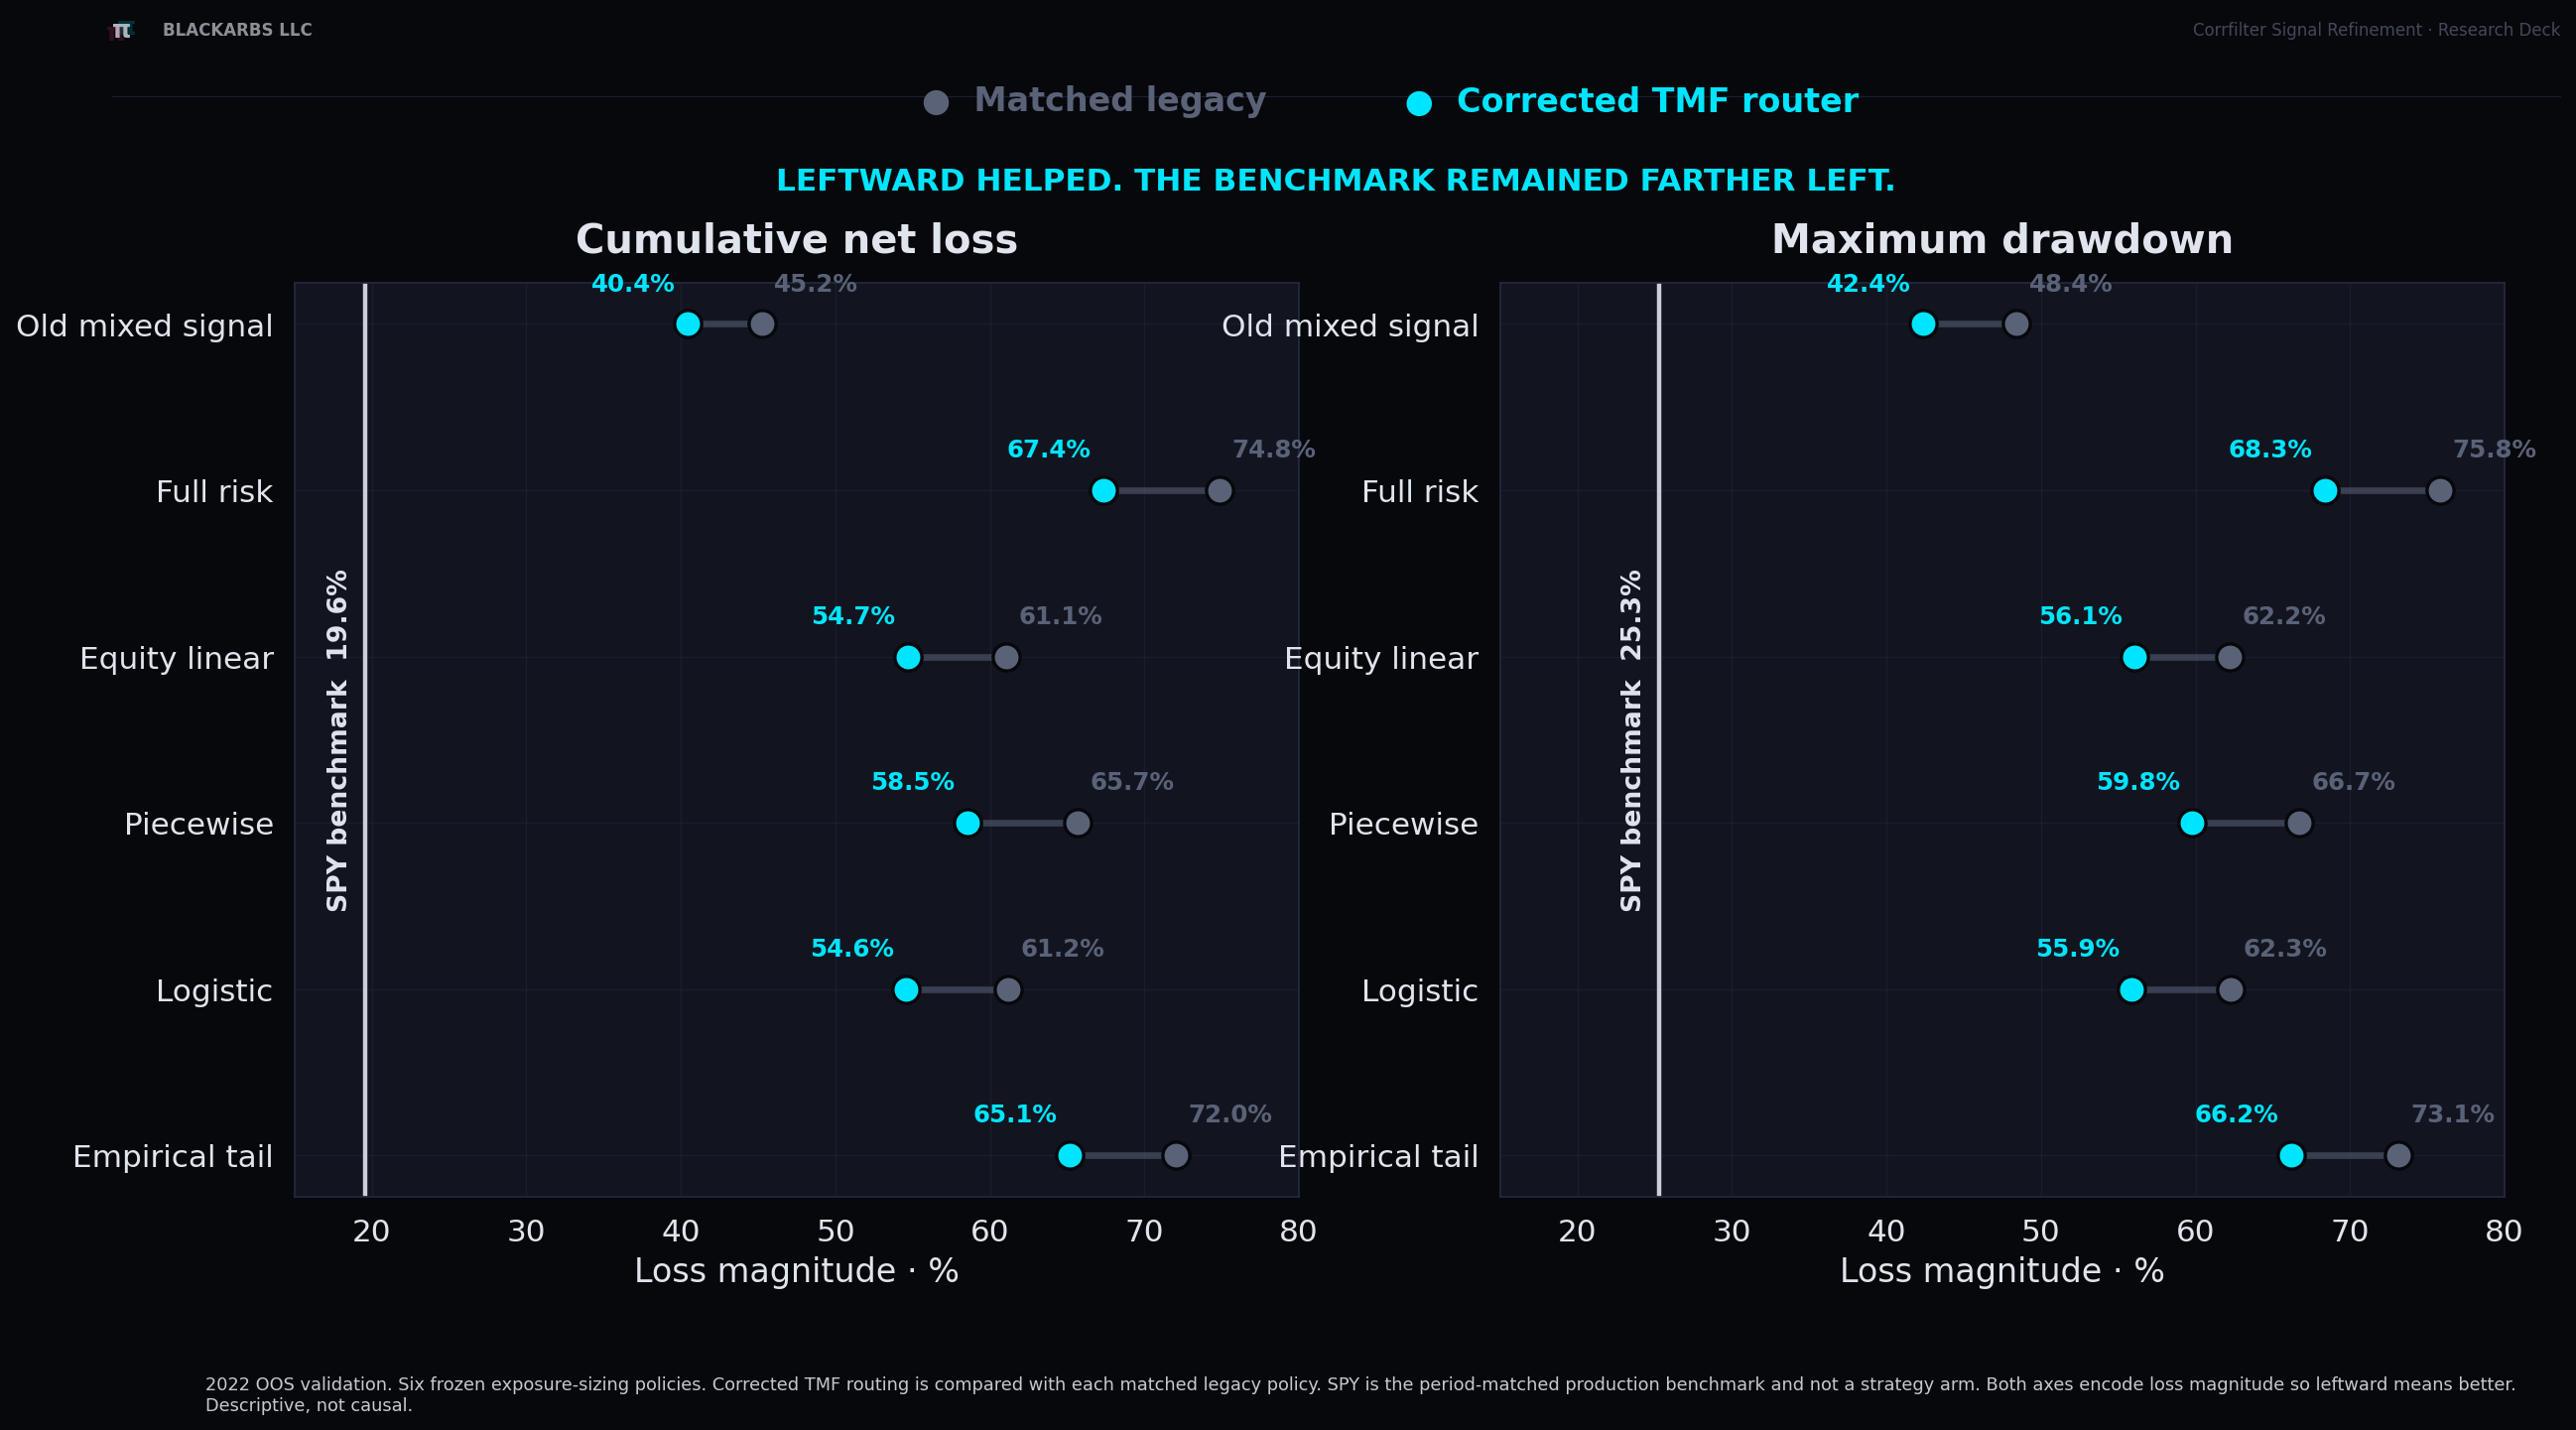
A strategy redesign looked dramatically better in sample. A 2022 out-of-sample test exposed the hidden leverage, and the strategy was rejected before the final holdout.
READ MORE →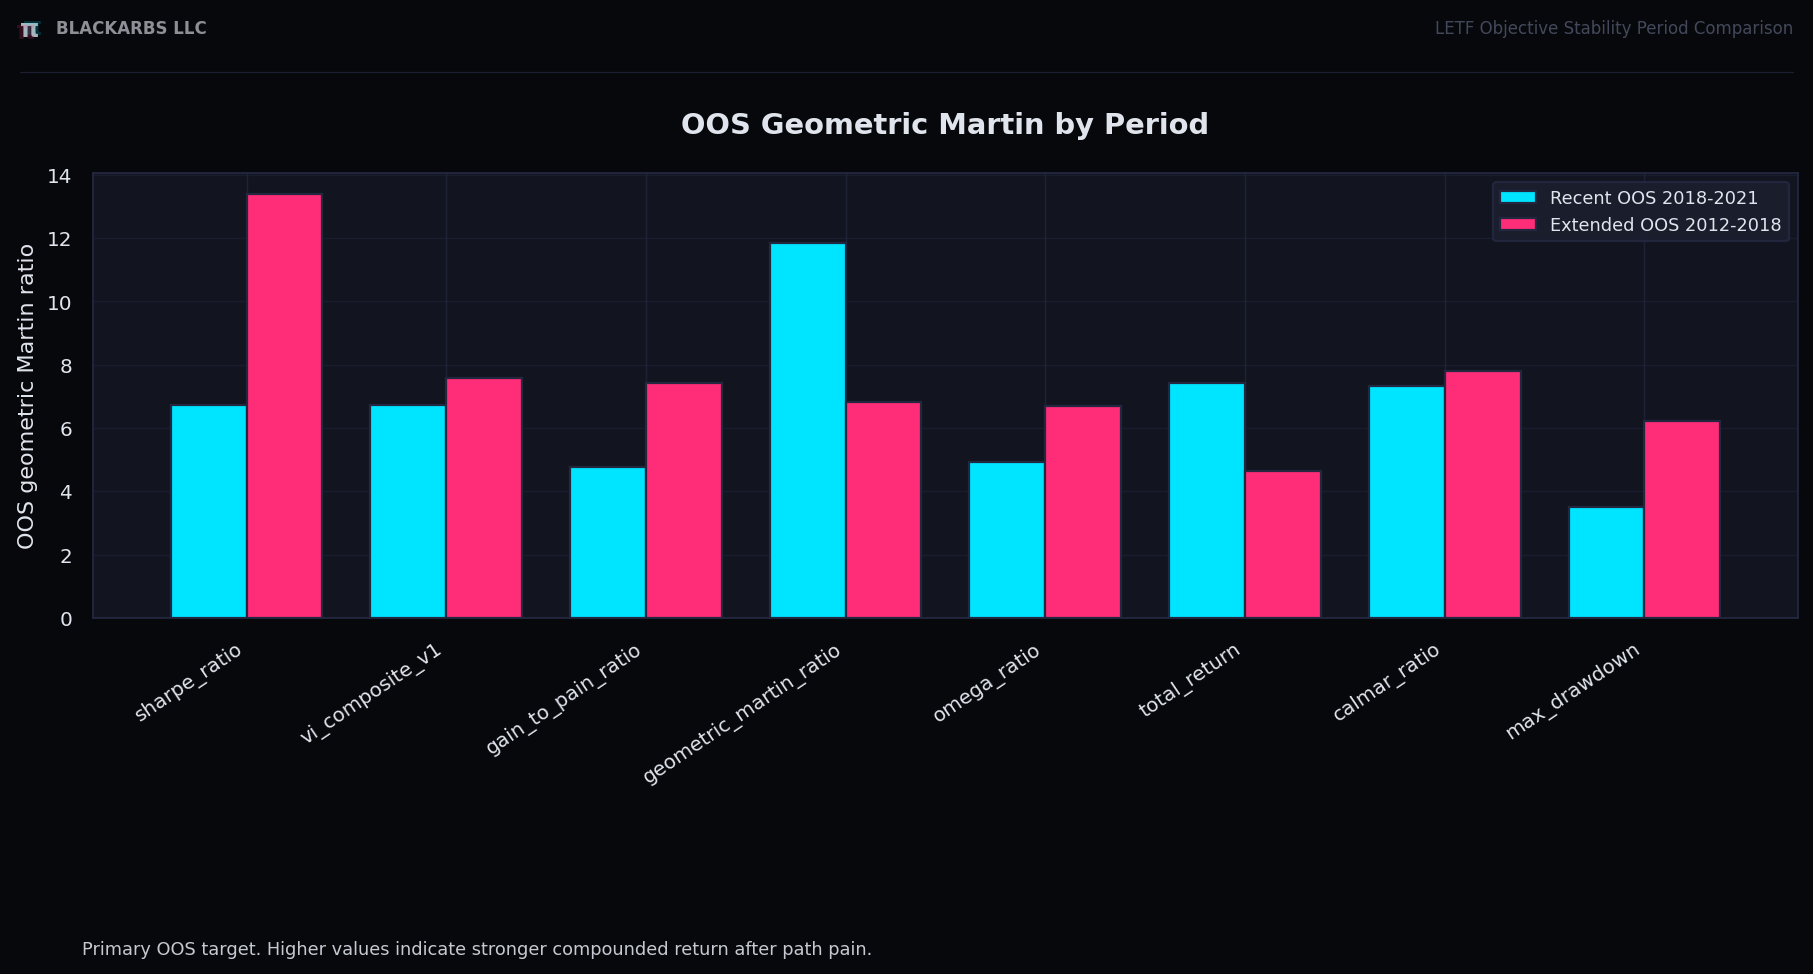
A walkforward optimizer objective test using geometric Martin as the out-of-sample path-quality judge.
READ MORE →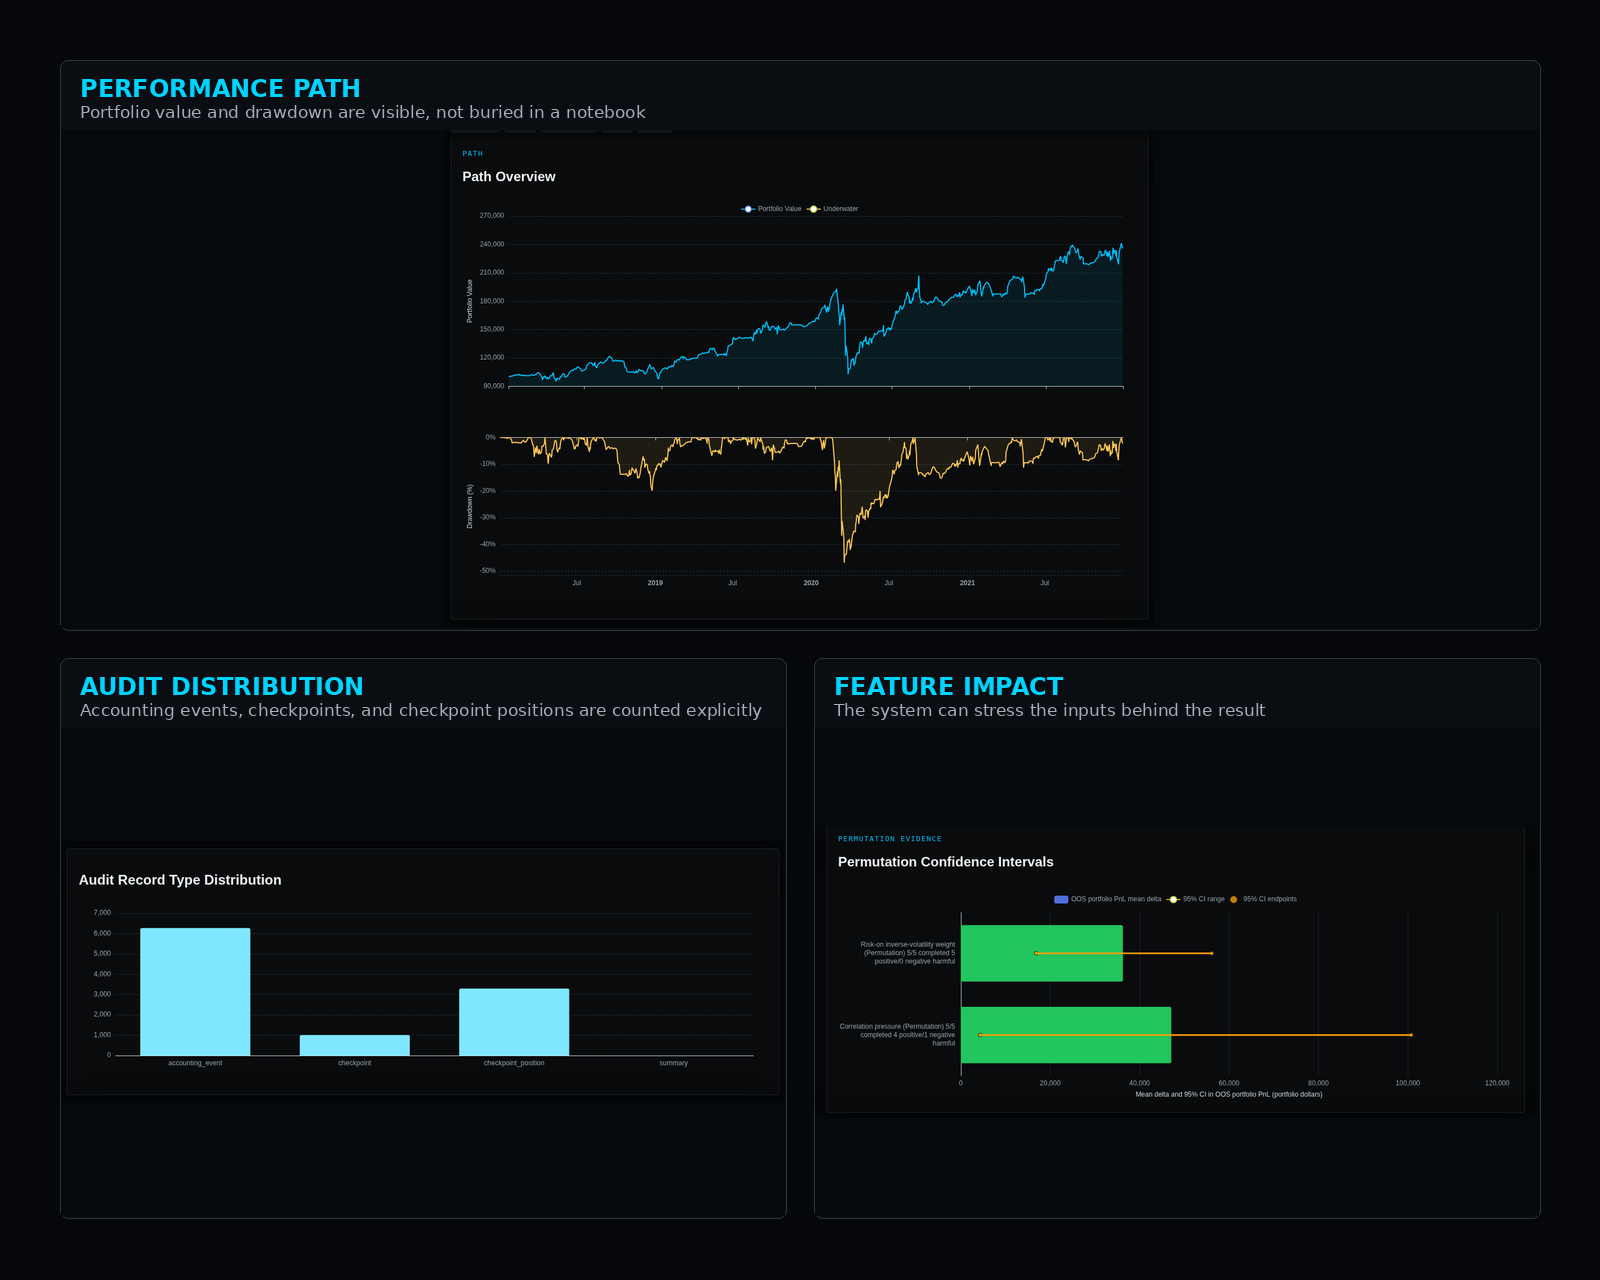
The first job of a serious research system is not to find alpha. It is to create the infrastructure where alpha can be trusted.
READ MORE →Get research updates, trading insights, and Python tutorials delivered to your inbox.
By clicking "Subscribe," you agree to our Terms of Use and acknowledge our Privacy Policy. You can unsubscribe at any time.
No spam. Unsubscribe anytime.